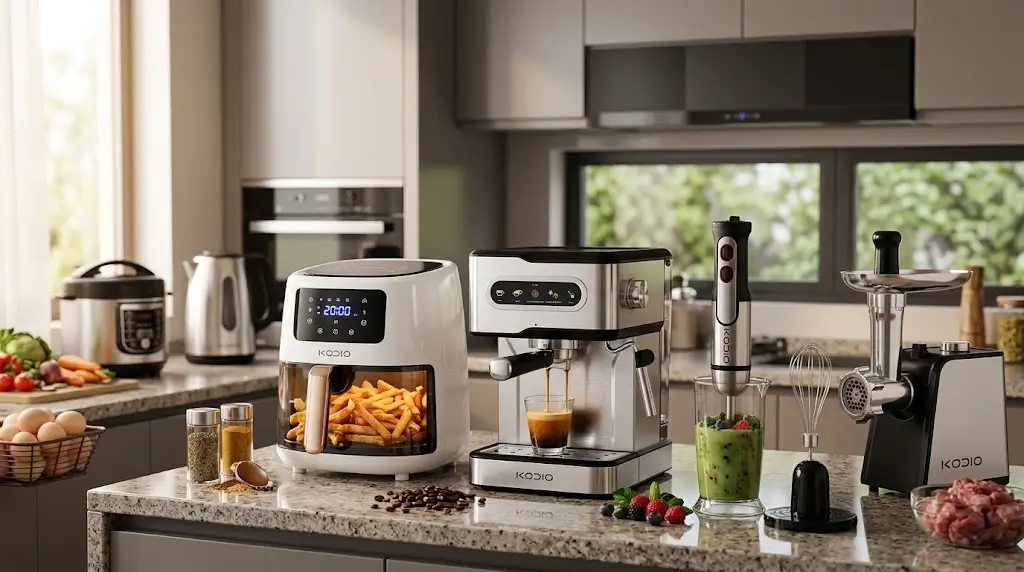
Air fryers now reside in over 60% of U.S. households, representing one of the fastest adoption cycles for any countertop device in history (Circana, 2023). This rapid hardware penetration pushed the U.S. small home appliance industry to $23.8 billion in annual sales. Simultaneously, hardware digitization is advancing, with 32% of newly upgraded kitchen devices featuring high-tech capabilities (Houzz, 2024). This article aggregates data from authoritative primary and research sources, including government energy surveys and independent industry tracking firms. Readers will understand the economic scale, household penetration, and technological shifts defining must-have small kitchen appliances.
Key Takeaways
- Air fryer penetration: Over 60% of U.S. homes own an air fryer, making it the dominant growth category of the decade (Circana, 2023).
- Market valuation: The U.S. small home appliance market generated $23.8 billion in retail revenue in 2023 (Circana).
- Coffee consumption: 67% of American adults drink coffee daily, sustaining continuous demand for electric brewers (National Coffee Association, 2024).
- Smart integration: 32% of homeowners who upgrade appliances select models with high-tech features (Houzz, 2024).
- Space utilization: 41% of kitchen renovators prioritize making better use of space, driving demand for multi-functional units (Houzz, 2024).
- Microwave saturation: Microwaves remain the most common countertop device, present in 96% of U.S. households (U.S. EIA).
- Energy consumption: Plug loads, which include countertop appliances, account for roughly 25% of total residential electricity use (U.S. EIA).
- Single-serve preference: Single-serve cup brewers are the primary preparation method for 32% of past-day coffee drinkers (National Coffee Association, 2024).
Market Size and Consumer Spending
The financial footprint of countertop cooking and beverage preparation remains heavily concentrated in daily-use categories. Coffee, espresso, and single-serve beverage makers consistently capture the largest dollar share within the industry. High daily consumption rates ensure steady replacement cycles for these machines.
The U.S. small home appliance industry reached $23.8 billion in retail sales in 2023.
| Metric | Value | Source |
| U.S. small appliance industry sales | $23.8 billion | Circana (2023) |
| Daily coffee drinkers (U.S. adults) | 67% | National Coffee Association (2024) |
| Single-serve brewer usage (past day) | 32% | National Coffee Association (2024) |
While total unit sales for small appliances experienced a slight post-pandemic normalization, total dollar sales remained elevated. Consumers are increasingly opting for premium, multi-functional models over entry-level, single-use units.
Source: Circana Small Appliance Industry Tracking
Household Penetration and Device Adoption
Appliance saturation varies significantly based on historical availability and culinary utility. Legacy categories have reached absolute market saturation, while newer convection categories achieved massive household penetration over a heavily compressed timeline.
Air fryers have reached over 60% household penetration in the U.S. market.
| Metric | Value | Source |
| Microwave ownership | 96% | U.S. EIA RECS (Most recent available) |
| Air fryer ownership | >60% | Circana (2023) |
| Toaster oven ownership | 42% | U.S. EIA RECS |
The air fryer reached 60% penetration in approximately five years. This represents a significantly faster adoption curve than the microwave, which required nearly two decades to reach similar levels of household integration.
Source: U.S. Energy Information Administration (EIA) Residential Energy Consumption Survey
Smart Technology Integration
The transition from analog controls to digital ecosystems is measurable, though adoption relies heavily on natural replacement cycles rather than preemptive upgrades. Consumers selecting smart kitchen appliances prioritize wireless connectivity, smartphone integration, and automated cooking presets.
32% of upgraded kitchen appliances feature high-tech capabilities, such as Wi-Fi connectivity or app controls.
| Metric | Value | Source |
| Upgraded appliances featuring high-tech capabilities | 32% | Houzz (2024) |
| Smart appliance ownership (US internet households) | 14% | Parks Associates (2023) |
| Consumers managing appliances via smartphone apps | 25% | Houzz (2024) |
There is a measurable gap between the purchasing of smart features and active daily usage. While nearly a third of new appliances possess high-tech capabilities, many consumers restrict their use of these features to initial setup or diagnostic alerts.
Source: Houzz 2024 U.S. Kitchen Trends Study
Kitchen Space Optimization
Physical footprint remains a primary constraint in residential kitchen design. Homeowners seeking the best small appliances for kitchen efficiency actively choose models that consolidate multiple culinary functions into a single unit. This preserves counter space and minimizes visual clutter.
41% of renovating homeowners rank making better use of space as their primary structural goal.
| Metric | Value | Source |
| Homeowners prioritizing better space utilization | 41% | Houzz (2024) |
| Homeowners prioritizing reduced clutter | 37% | Houzz (2024) |
| Homeowners replacing all appliances during a remodel | 54% | Houzz (2024) |
The demand for space saving kitchen appliances directly influences manufacturing lines. This shift has resulted in the proliferation of combination air fryer-toaster ovens and digital multi-cookers that eliminate the need for standalone rice cookers, slow cookers, and traditional toasters.
Source: Houzz 2024 U.S. Kitchen Trends Study
Energy Consumption and Efficiency
Countertop devices materially impact overall residential energy profiles. While individual small units draw less total annual power than central HVAC systems, their aggregate plug load requires continuous baseline electricity generation.
Plug loads account for approximately 25% of residential electricity consumption.
| Metric | Value | Source |
| Residential electricity used by plug loads | 25% | U.S. EIA |
| Energy savings of ENERGY STAR coffee makers | Up to 35% | U.S. EPA / ENERGY STAR |
| Homes using a microwave at least once daily | 70% | U.S. EIA RECS |
An electric kitchen appliance like an ENERGY STAR certified coffee maker achieves its 35% efficiency gain primarily through improved internal insulation and optimized heating elements. These hardware adjustments reduce the total wattage required to maintain water temperature between brewing cycles.
Source: ENERGY STAR Appliance Efficiency Metrics
Must Have Small Kitchen Appliances by the Numbers
| Metric | Value | Source |
| U.S. small appliance industry retail sales | $23.8 billion | Circana (2023) |
| Air fryer household ownership | >60% | Circana (2023) |
| Microwave household ownership | 96% | U.S. EIA |
| Toaster oven household ownership | 42% | U.S. EIA |
| Daily coffee drinkers (U.S. adults) | 67% | NCA (2024) |
| Single-serve brewer usage (past day) | 32% | NCA (2024) |
| Upgraded appliances with high-tech capabilities | 32% | Houzz (2024) |
| Smart appliance ownership (US internet households) | 14% | Parks Associates (2023) |
| Consumers managing appliances via apps | 25% | Houzz (2024) |
| Homeowners prioritizing better space utilization | 41% | Houzz (2024) |
| Homeowners prioritizing reduced clutter | 37% | Houzz (2024) |
| Homeowners replacing all appliances during remodel | 54% | Houzz (2024) |
| Residential electricity used by plug loads | 25% | U.S. EIA |
| Energy savings of ENERGY STAR coffee makers | Up to 35% | U.S. EPA |
| Homes using a microwave at least once daily | 70% | U.S. EIA |
Sources
- Circana (formerly IRI and NPD Group): 2023 U.S. Small Appliance Industry Tracking and Sales Data.
- Houzz: 2024 U.S. Kitchen Trends Study.
- National Coffee Association (NCA): 2024 National Coffee Data Trends (NCDT) Report.
- U.S. Energy Information Administration (EIA): Residential Energy Consumption Survey (RECS) and Plug Load Baseline Data.
- U.S. Environmental Protection Agency (EPA): ENERGY STAR Program Requirements and Appliance Efficiency Specifications.
- Parks Associates: 2023 Smart Home Device Adoption and Internet Household Data.